Adani Power Signs Agreement for 770 MW Hydropower Project in Bhutan
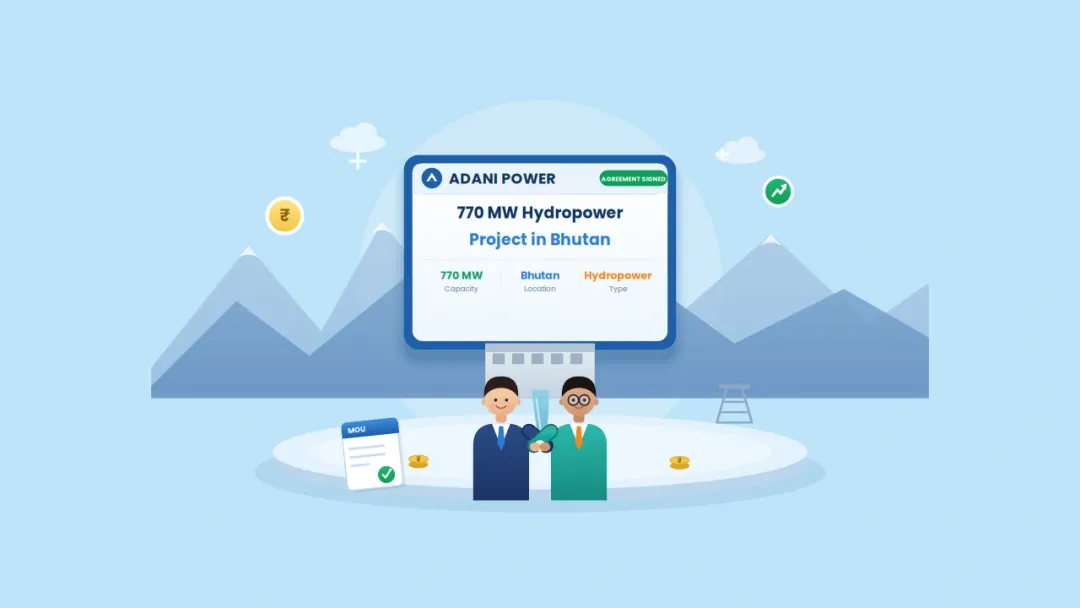
“Adani Power has entered into a shareholders agreement with Druk Green Power Corporation to jointly develop a 770 MW hydropower project in Bhutan.”
Adani Power and DGPC Sign Shareholders Agreement
Adani Power and DGPC have signed a Shareholders Agreement (SHA) to jointly develop the 770 MW Chamkharchhu-I Hydropower Project in Bhutan. The agreement was signed on October 5, 2026, and involves setting up a public company in Bhutan to undertake the project.
49:51 Equity Partnership
- Adani Power will hold 49%, while DGPC will hold 51% in the project company.
- Both partners can appoint three directors each to the board.
- Adani Power will subscribe to 4.9 million shares, while DGPC will subscribe to 5.1 million shares at BTN 100 per share.
What to Watch Next
Investors may track the formation of the project company, progress toward construction in 2027 and the project's execution timeline. The development also strengthens Adani Power's presence in Bhutan's hydropower sector.
Disclaimer
Investments in the securities market are subject to market risks. Read all related documents carefully before investing. Registration granted by SEBI, and certification from NISM in no way guarantee the performance of the intermediary or provide any assurance of returns to investors. Choice Equity Broking Private Limited: SEBI Reg No. Broking - INZ000160131 ( BSE - 3299 ) | ( NSE - 13773 ) | ( MSEI - 73200 ) | ( MCX - 40585 ) | ( NCDEX - 01006 ). Depository Participant SEBI Reg. No. - IN - DP - 84 - 2015, DP ID CDSL - 12066900, NSDL ID - IN301895. Research Analyst - INH000000222 (CIN. NO.: U65999MH2010PTC198714)
Other News
Aluminium Price Prediction for Next Week
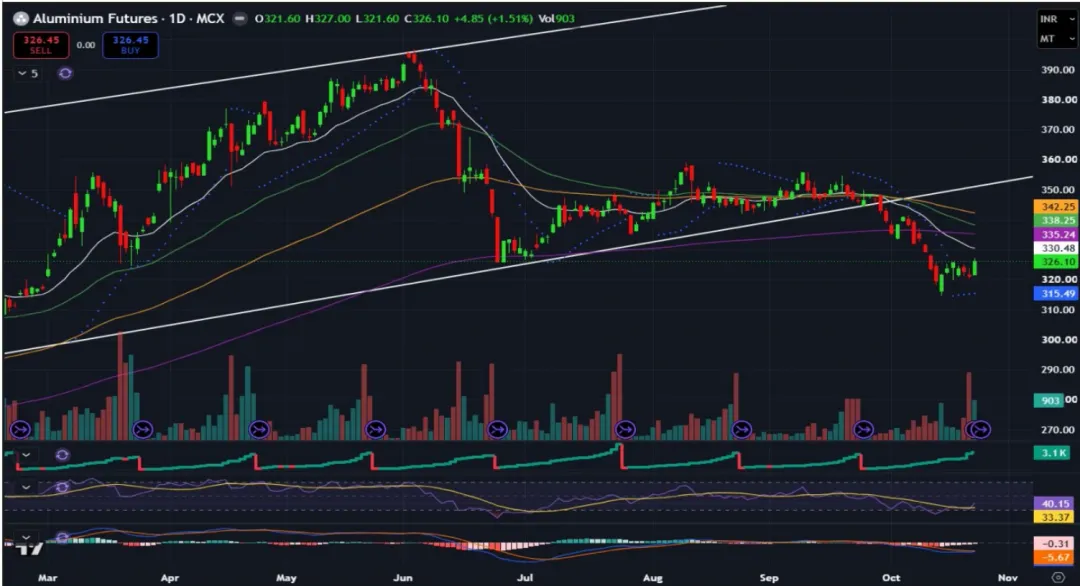
LME Aluminium prices closed the week higher, supported by Middle East supply disruptions and relatively low raw material costs, which encouraged Chinese smelters to maintain high production levels. Despite, China's aluminium product output declined 1.2% year-on-year to around 4.8 million tonnes in September, indicating weakness in downstream demand. However, Chinese aluminium exports increased 25.9% year-on-year, reaching a three-month high, while Indonesian exports exceeded 150,000 tonnes in August. Meanwhile, Middle Eastern smelters are gradually recovering, with Al Taweelah targeting full production recovery by Q1 2027. Easing physical premiums and Rio Tinto's extension of Bell Bay operations through 2031 indicate improving supply prospects, potentially limiting further price gains.
Copper Price Forecast for Next Week
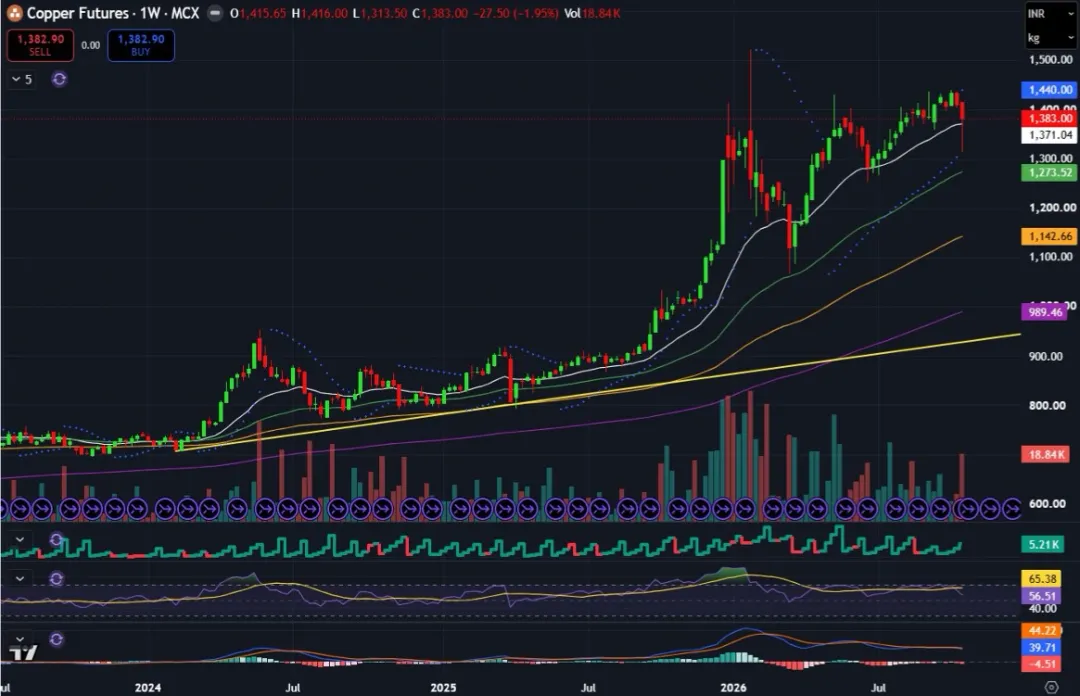
LME Copper prices declined for the second consecutive week as a global selloff in artificial intelligence stocks dampened sentiment toward the metal. Concerns over elevated inventories persisted, with LME stocks rising 20% over the week to 273,750 tonnes, despite a modest increase of 800 tonnes on Friday. However, inventories registered with the Shanghai Futures Exchange fell 26.5% weekly, indicating tightening availability in China. Meanwhile, substantial copper stockpiles in the US continued to weigh on prices amid uncertainty over potential tariff measures and the risk of re-exports. Despite near-term weakness, copper retains long-term support from AI-driven data centre and power infrastructure expansion. Supply risks also remain elevated due to potential labour strikes at major mining operations and uncertainty surrounding US trade policies.
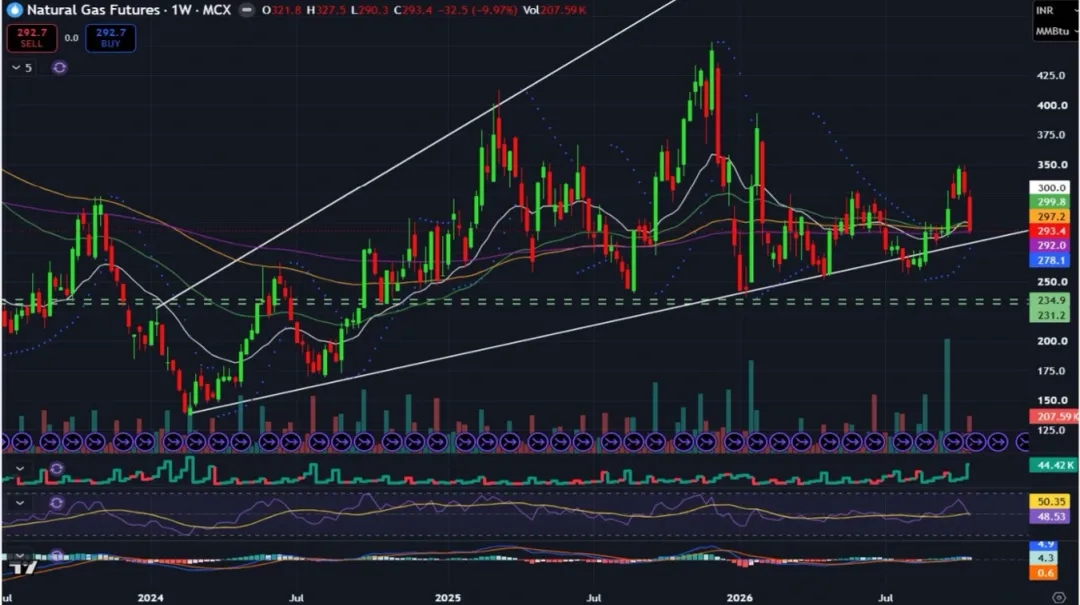
Natural Gas Price Prediction for Next Week
US Natural gas prices declined over 6% during the week amidst forecasts for warmer weather near term limits consumption demand. Above-average temperatures across the Midwest and East through November 5 are expected to limit heating demand. The bearish sentiment outweighed support from a below-average storage injection of 77 Bcf for the week ended October 16, lower US production of 111.4 Bcf/d and stronger LNG feedgas demand, which rose in October. Meanwhile, speculative net short positions increased by 26,764 contracts to 126,900 contracts, reflecting weaker market sentiment. However, geopolitical uncertainty, Middle Eastern LNG shipments remaining around 80% below year-ago levels and EU gas storage at 74.62% could intensify global supply competition, limiting further downside.