Juniper Green Energy Reports Strong Q2 FY27 Results, Turns Profitable

“The company’s EBITDA increased 162% YoY to Rs.339.55 crore, with its EBITDA margin expanding to 91.36%.”
Juniper Green Energy Returns to Profit in Q2 FY27
Juniper Green Energy reported an improvement in its financial performance during Q2 FY27, returning to profitability compared with the loss recorded in the corresponding quarter last year. The company recorded growth across key financial indicators, supported by its renewable energy portfolio and operational progress.
Cash PAT also registered strong growth, while the company continued to expand its renewable energy and battery energy storage system (BESS) capacity.
Financial and Operational Highlights
- Total Income: Rs.371.64 crore, up 132% YoY.
- EBITDA: Rs.339.55 crore, up 162% YoY.
- EBITDA Margin: 91.36%, expanding by 1,034 basis points.
- Profit After Tax (PAT): Rs.53.56 crore, compared with a loss of Rs.18.40 crore in Q2 FY26.
- Cash PAT: Rs.152.55 crore, up 285% YoY.
- New Capacity Commissioned: 1,036 MWp of renewable energy capacity and 503 MWh of BESS during the first seven months of FY27.
- Operational Portfolio: 2,844 MWp of renewable energy capacity and 604 MWh of BESS.
- BESS Targets: 4,500 MWh by June 2027 and 10,000 MWh by March 2028.
- Credit Rating: ICRA upgraded the company's rating to AA- with a Stable outlook.
- Capital Expenditure: Rs.18,895 crore incurred up to September 30, 2026, including Rs.2,591 crore during Q2 FY27.
- Power Purchase Agreements: Around 98% of the company's 11.2 GWp portfolio is secured through long-term PPAs, typically spanning 25 years.
What to Watch Next
Investors will monitor Juniper Green Energy's progress on planned BESS installations, capacity commissioning and execution of its secured renewable energy portfolio. The company's ability to sustain profitability and achieve its expansion targets will remain important in the coming quarters.
Disclaimer
Investments in the securities market are subject to market risks. Read all related documents carefully before investing. Registration granted by SEBI, and certification from NISM in no way guarantee the performance of the intermediary or provide any assurance of returns to investors. Choice Equity Broking Private Limited: SEBI Reg No. Broking - INZ000160131 ( BSE - 3299 ) | ( NSE - 13773 ) | ( MSEI - 73200 ) | ( MCX - 40585 ) | ( NCDEX - 01006 ). Depository Participant SEBI Reg. No. - IN - DP - 84 - 2015, DP ID CDSL - 12066900, NSDL ID - IN301895. Research Analyst - INH000000222 (CIN. NO.: U65999MH2010PTC198714)
Other News
Fabtech Cleanrooms Reports 74.88% Revenue Growth in H1 FY27; Order Book Reaches Rs 470 Crore
Fabtech Cleanrooms Limited (formerly Fabtech Technologies Cleanrooms Limited) has announced its unaudited standalone and consolidated financial results and business highlights for the half year ended September 30, 2026 (H1 FY27). The company reported a 74.88% year-on-year increase in consolidated revenue from operations to Rs.133.23 crore, compared with Rs.76.19 crore in H1 FY26. EBITDA increased by 75.13% to Rs.10.28 crore, while EBITDA margin stood at 7.67%. Consolidated Profit After Tax (PAT) stood at Rs.5.15 crore, registering a 54.65% year-on-year growth compared with Rs.3.33 crore in the corresponding period of the previous financial year. Fabtech Cleanrooms also reported its highest-ever order book of approximately Rs.470 crore, more than double the Rs.199 crore recorded as of March 31, 2026. The company has an active order pipeline of Rs.600 crore out of a total offered pipeline of Rs.1,250 crore.
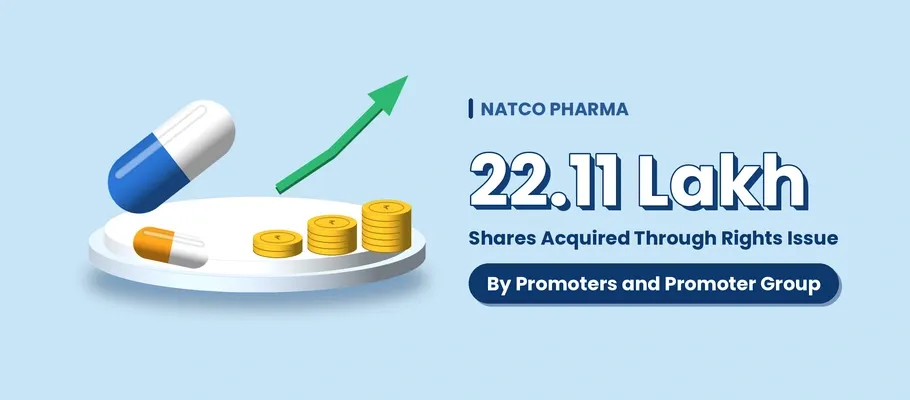
Natco Pharma Promoters and Promoter Group Acquire 22.11 Lakh Shares Through Rights Issue
Natco Pharma Limited’s promoters and promoter group entities have acquired 22,11,776 equity shares through the company’s Rights Issue. The shares were allotted on October 26, 2026, at Rs 750 per share, taking the total value of acquisition to about Rs. 165.88 crore. The company’s paid up equity share capital increased to 19,61,67,952 equity shares following the Rights Issue.
Jio Financial Services Allots 25 Crore Shares to Promoter Group Entities
Jio Financial Services Limited has allotted 25 crore equity shares to two promoter group entities following the conversion of preferential warrants. The allotment was made at Rs.316.50 per share, including a face value of Rs.10 and a premium of Rs.306.50 per share.